Individual Economists

57 California Dams In Poor Or Unsatisfactory Condition, State Auditor Says

Zero Hedge -

57 California Dams In Poor Or Unsatisfactory Condition, State Auditor Says

Authored by Naveen Athrappully via The Epoch Times,

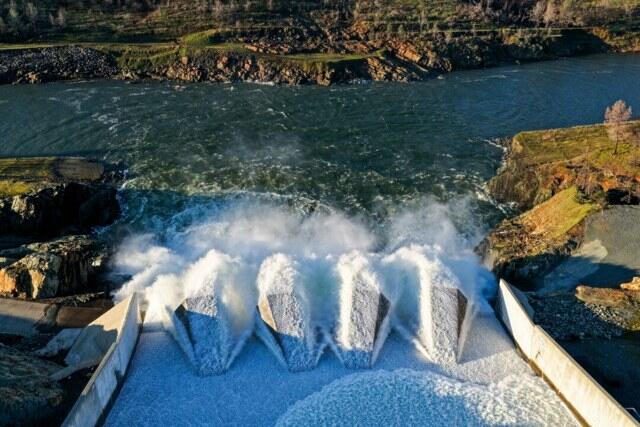
A new report from the state auditor says 57 dams in California are in poor or unsatisfactory condition, posing a safety risk to hundreds of thousands of residents.

Out of those 57 dams, 40 have "high or extremely high" hazard classifications as of May, the Oct. 13 report said.

"Failure of just one of these 40 high or extremely high hazard dams could pose harm to as many as hundreds of thousands of people and cause billions of dollars in property damage," the auditor warned, citing the Department of Water Resources' (DWR's) assessment of 1,222 Californian dams.

The most common factors for the poor conditions are old age, the inability to pay for repair costs, and the lack of comprehensive safety standards in effect when the dams were built, the report said.

While the DWR has enforcement authority over dams, it has "only sent notices of violations to dam owners but has not taken further actions, thereby allowing serious deficiencies to persist," the auditor said.

The department stated that limited resources hindered efforts to repair dams before they failed.

Of the 1,222 dams, the auditor found that owners of 60 dams with higher hazard classifications did not comply with California law requiring they submit emergency action plans aimed at protecting life and property in case of structure failure.

Local maintaining agencies (LMAs) were charged with maintenance of levees - structures that help contain or control water flow during floods.

In the report, the auditor wrote that LMAs were lacking when it came to levee maintenance, while the DWR was reluctant to intervene, posing heightened risks to communities.

California Gov. Gavin Newsom proclaimed an emergency last month to prepare the state for El Niño, when southern areas of the state face increased rainfall and flash flooding.

The largest impacts of El Niño typically affect the United States from October through May.

In the emergency declaration, Newsom highlighted the risks posed to dams by El Niño conditions.

In the proclamation, Newsom ordered the DWR to contact dam owners and remind them of their responsibility to repair, maintain, and safely manage dams and other structures.

Meanwhile, the California state auditor's report included a response from the DWR regarding the draft version of the document.

The response criticized the audit report for portraying a "fundamental lack of understanding" of the complexities involved in flood management and dam safety.

The DWR said the audit misrepresents that poor maintenance and lack of action are the sole reasons for dams being in unsatisfactory condition.

"This further demonstrates the lack of technical understanding that the most critical deficiencies are found through DWR's reevaluation program; these are not visible in an inspection and most often occur because design loads (earthquakes and floods) are larger than originally expected," the department said.

"Design standards, engineering methods, and science have changed over time. These dams were not necessarily built poorly."

The DWR's reevaluation program periodically reviews dams deemed to pose a threat to life against current dam safety standards.

The department said that the program is responsible for detecting more than two-thirds of dam deficiencies.

In a Sept. 30 statement, the DWR announced completing a $235 million rehabilitation of California's Oroville Dam, the tallest in the United States.

"This investment in Oroville Dam's infrastructure ensures the reliable and safe operation of the State Water Project's largest flood protection and water supply facility," John Yarbrough, deputy director of the DWR's State Water Project, said in the statement.

Dam safety is a wider national issue as well.

According to a report from the American Society of Civil Engineers, almost 17,000 dams in the United States are considered potentially high hazard.

The report highlighted that the average age of dams in the United States is more than 60 years, with seven out of 10 estimated to be at least 50 years old in 2025.

"Without a more significant commitment to dam safety through increased annual investment in inspection, monitoring, planning, and necessary dam repairs, the cost to bring the nation's dams into a state of good repair will continue to rise," the association said.

"And downstream communities will face a greater risk of danger from potential dam failure."

Tyler Durden Thu, 10/15/2026 - 15:50

Iran War Has Cost Nearly $2,000 Per US Household: Moody's Top Economist

Zero Hedge -

Iran War Has Cost Nearly $2,000 Per US Household: Moody's Top Economist

Moody's Analytics chief economist Mark Zandi estimated Oct. 12 that the Iran war has cost the average U.S. household nearly $2,000 since it began, or about $265 billion nationwide. He put roughly $1,100 per household on higher energy and transportation costs, $540 on higher interest rates and $360 on military spending, and said the energy tab is still rising by about $50 per household each week at current fuel prices.

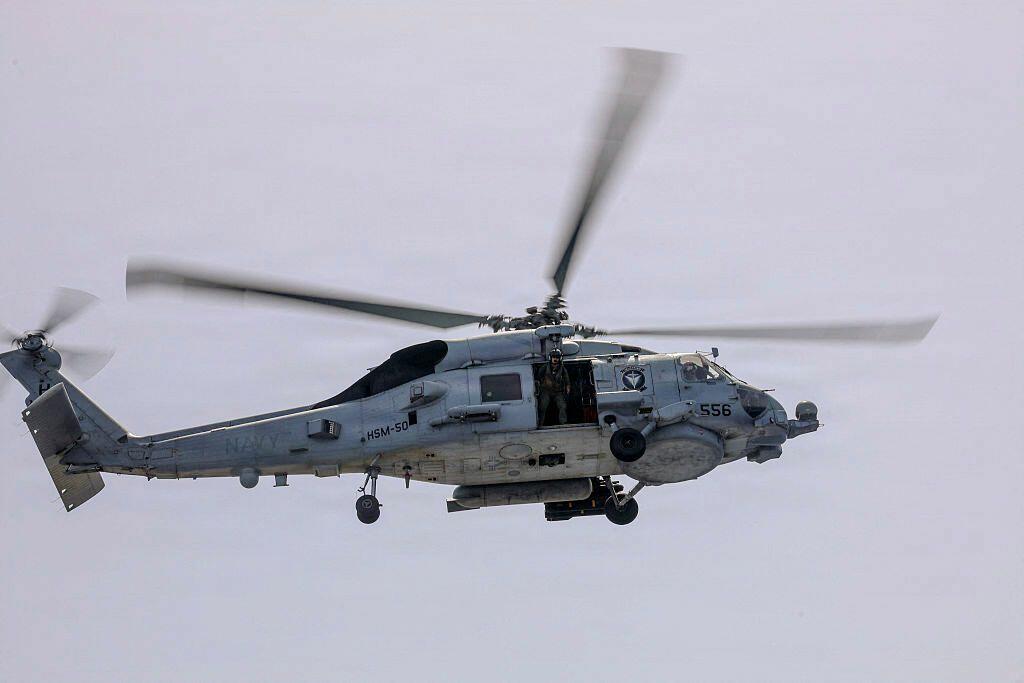
An MH-60R Sea Hawk helicopter, assigned to Helicopter Maritime Strike Squadron 50, takes off from the flight deck of the Arleigh Burke-class guided-missile destroyer USS Thomas Hudner on May 4, 2026. US NAVY/AFP via Getty Images

Zandi wrote on X: "Consider that the war's costs taken together have absorbed about half the average American household's income gain over the past eight months. No wonder the war is so unpopular."

White House Principal Deputy Press Secretary Anna Kelly answered in a statement: "Mark Zandi is a Democrat donor who is frequently wrong - including predicting multiple recessions that never happened." She added: "President Trump is rightfully ensuring that Iran, a country that for 47 years chanted 'Death to America,' can never have a nuclear weapon." U.S. and Israeli strikes on Iran began Feb. 28.

Zandi's number is a broad economic estimate, not a federal outlay. Brown University puts consumer costs at $133.3 billion, about $1,018 per household, and Defense Secretary Pete Hegseth has testified to about $37.5 billion in direct military costs, Newsweek reported. ZH has tracked estimates running well above the White House's.

As the Epoch Times notes further, "Higher energy prices are contributing most to the costs," Zandi said. "A gallon of regular goes for $4.37, up from just under $3 before the war. Diesel is above $6, and jet fuel has nearly doubled. As winter approaches, the much higher price of home heating fuel is also adding to the costs."

Zandi said the war's inflation contributed to the Fed's decision last month to raise rates and signal that more rate increases are coming.

"Long-term rates are also up a lot - fixed mortgage rates have climbed from below 6 percent before the war to 7.5 percent. By our reckoning, the higher rates have cost the economy about $540 per household," he said.

In September, the Congressional Budget Office estimated the war cost the U.S. military $38.1 billion through Aug. 1. With fighting expected to continue, the war was estimated to cost between $2 billion and $3 billion each month, depending on its intensity.

On Oct. 5, the Congressional Research Service published a report listing some of the major equipment losses during the war.

The report listed 81 fixed-wing or rotary-wing aircraft, including drones that were lost or damaged during the conflict.

The Congressional Budget Office estimated the cost of equipment losses as of Aug. 1 to be between $1.9 billion and $3.3 billion, depending on the Department of War's plans for replacement.

Democrats have continually pointed to the cost of the war in their criticism of Trump.

In September, 46 Democratic or left-leaning Independent Senators sent a letter to Department of War Secretary Pete Hegseth demanding more information on the costs of the war.

Tyler Durden Thu, 10/15/2026 - 15:35

Time's Up! DOJ To Seek 'Emergency Relief' Against California Over Suspected Non-Citizen Voters

Zero Hedge -

Time's Up! DOJ To Seek 'Emergency Relief' Against California Over Suspected Non-Citizen Voters

Authored by Tom Gantert via The Epoch Times,

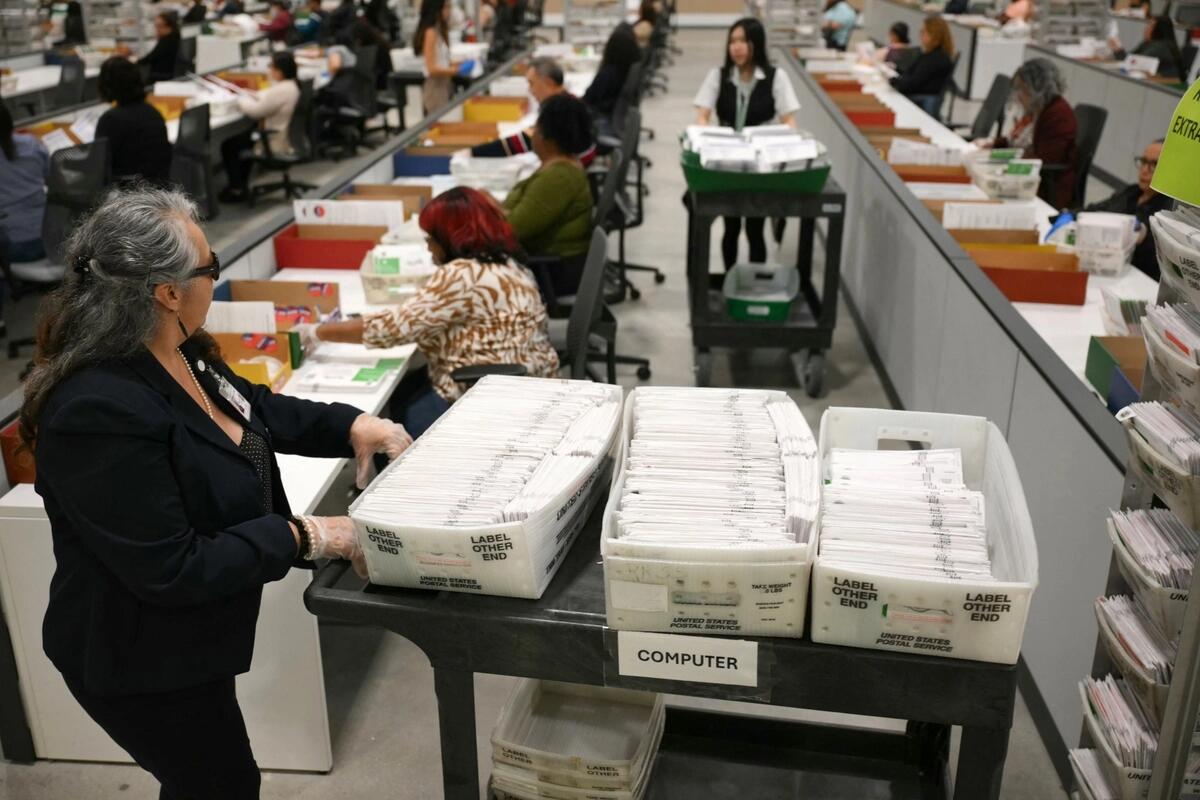
The U.S. Department of Justice on Oct. 13 sent letters to California election officials demanding a review within 48 hours of registered voters it suspects are noncitizens and asking officials to set aside their mail ballots until their citizenship status can be determined.

If the prescribed course of action wasn't followed by Oct. 15 at noon ET, the letter stated the federal government would seek "emergency relief."

"This should not be controversial, as the criminal statute is clear: Only American citizens may vote in federal elections. It is a federal crime for noncitizens to vote in U.S. elections, and the DOJ is asking California to ensure that is not occurring," a DOJ spokesperson said in an email to The Epoch Times.

The DOJ claims there are thousands of potential foreign nationals not eligible to vote that have been identified as registered voters in California.

Dean Logan, registrar for Los Angeles County, posted a copy of the DOJ's letter on the county clerk website.

In the letter to Los Angeles County, the DOJ stated that Department of Homeland Security Secretary Markwayne Mullin informed the California secretary of state that there are "likely numerous noncitizens" registered to vote in the federal election in California.

"Accompanying this letter is a password-protected thumb drive with a list of names of people the Federal Government believes are likely noncitizens who were sent a vote-by-mail ballot from California to participate in the November election," the letter stated.

The letter requested that L.A. County review the list within 48 hours. For any individuals the county could not independently verify as citizens, the letter requested election officials be instructed to "segregate - not cancel" those vote-by-mail ballots until their citizenship status could be determined.

If the county didn't comply with the DOJ request, the letter stated, "the United States will have no choice but to seek emergency relief."

Logan said his office has not accessed the drive because doing so would conflict with "established data privacy and information security protocols." He said his office does not consider the device a secure medium and said the letter does not specify the number of individuals involved or describe the information contained in the records.

"Maintaining accurate voter registration records is a fundamental responsibility of our office," Logan said in a statement. "Federal and state laws are clear on how voter eligibility is established - and any action to remove a voter from eligibility must be based on verifiable information, not assertions of unconfirmed data matching."

Logan said that with the 2026 general election underway, his department is focused on administering a safe, secure, accurate, and transparent election.

"We will continue following established legal requirements and verification procedures while protecting the rights of every eligible voter," Logan stated.

Gov. Gavin Newsom's press office posted Wednesday on X in response to the letter.

"With this letter, the Trump administration is demanding that California election officials voluntarily violate federal law enshrined by Congress. Completely unacceptable and inappropriate for the feds to do - especially with their track record," the statement said, not specifying what federal law would be violated.

The California Secretary of State also criticized the DOJ's letter in a response on X.

"The US DOJ's relentless efforts to unlawfully gain access to states' protected voter data and purge voter rolls serve only to cause chaos and fuel public distrust in our elections," the statement said. "California has robust state law requirements that only U.S. citizens can register to vote and that any non-eligible registrants are removed from the State's voter rolls."

Tyler Durden Thu, 10/15/2026 - 15:20

RFK Jr. Removes 189,000 Improper Health Care Enrollments

Zero Hedge -

RFK Jr. Removes 189,000 Improper Health Care Enrollments

Authored by AG News Staff via American Greatness,

Health and Human Services Secretary Robert F. Kennedy Jr. announced Wednesday that the Trump administration has eliminated 189,000 improper government-subsidized health care enrollments, a move expected to save American taxpayers as much as $1.5 billion annually.

The Centers for Medicare and Medicaid Services (CMS) identified duplicate enrollments and coverage associated with deceased individuals across Medicare, Medicaid and the Children's Health Insurance Program (CHIP).

The sweeping cleanup is part of the administration's broader effort to eliminate wasteful government spending and prevent taxpayer dollars from flowing to insurance companies through improper subsidies.

"In 2026, CMS identified 189,000 subsidized enrollments involving duplicate Medicare, Medicaid, or CHIP coverage on record showing the enrollee has died," Kennedy said during a news conference.

"CMS acted to remove improper subsidies in all these cases."

According to Kennedy, the action will save taxpayers approximately $738 million in 2026, with projected annual savings reaching $1.5 billion in subsequent years.

The HHS secretary emphasized that the improper payments benefited insurance companies rather than Americans receiving medical care.

"Each of those figures represents a payment that would otherwise have gone to an insurance company, not to an American citizen," Kennedy said.

To safeguard against wrongful removal, CMS contacted affected enrollees or their estates and provided a 30-day window to correct potential errors before subsidies were terminated.

Tyler Durden Thu, 10/15/2026 - 14:50

New DRAM Demand Source Could Surge 20-Fold By 2030

Zero Hedge -

New DRAM Demand Source Could Surge 20-Fold By 2030

Last month, Jason Chen, chairman and CEO of Taiwanese PC maker Acer, offered some relief from the memory shortage, saying chip prices could begin falling in the second half of next year. That outlook challenges the memory cartel, pardon, the Big Three's claims that prices will keep rising well beyond 2027.

Meanwhile, Chinese memory-chip manufacturer ChangXin Memory Technologies, better known as CXMT, recently said it had begun mass production of advanced memory chips. Goldman analysts are now looking to Samsung's Oct. 29 earnings report for indications of whether the company expects tight memory-market conditions to persist in 2028.

AI hyperscalers have soaked up the world's high-bandwidth memory (HBM) for the data center buildout, sending prices soaring and pressuring consumer electronics companies such as Apple, which was forced to raise prices for the new iPhone 18 premium lineup and foldable Duo.

But with CXMT's supply coming online and major memory giants still warning of tight conditions through next year, we may soon see whether that narrative holds after Samsung's earnings call. A new source of memory demand could also emerge, this time outside data centers and in physical AI.

Counterpoint Research forecasts that DRAM demand could surge with the coming wave of humanoid robot deliveries, expected to begin next year and continue through the decade.

South Korean newspaper The Chosun Daily first cited Counterpoint's note, which said DRAM demand for humanoid robots could explode to 172,000 terabits in 2030 from roughly 8,300 terabits this year.

Average DRAM capacity per humanoid robot is set to roughly double, from 19 gigabytes to 39 gigabytes, over the same period.

More sophisticated AI models have increasingly larger and larger memory requirements, and we're sure those requirements could rise even further. These complex bots process images, video and sound simultaneously and use "world models" to anticipate changes in the surrounding environment, requiring faster processing and greater memory capacity.

Beyond humanoid robotics, memory demand will likely surge for highly autonomous vehicles, which typically require over 200 GB of memory and several terabytes of storage.

Global memory firms are eyeing the robot market. Sanjay Mehrotra, Micron CEO, recently said, "Level 4 or higher autonomous vehicles typically require over 200 GB of memory and several terabytes of storage. Humanoid robots will likely need similar levels of memory and storage."

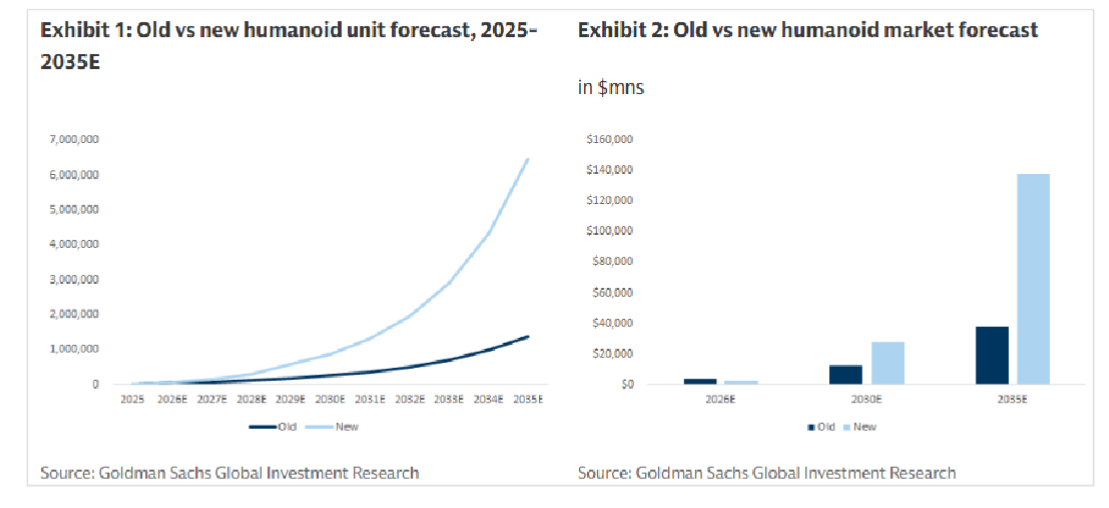
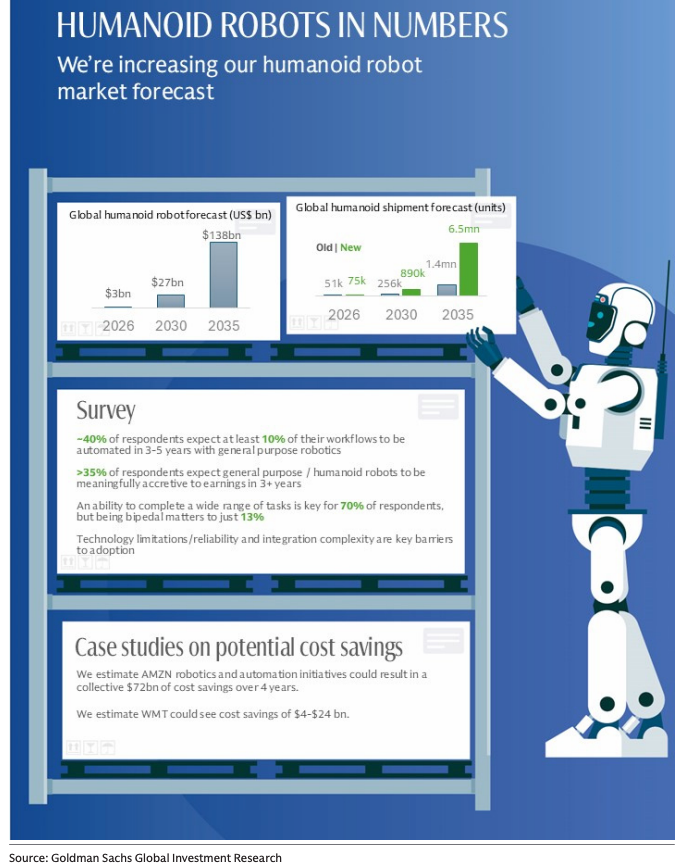
On the demand side of humanoid robotics, Eric Sheridan, managing director and internet/e-commerce equity analyst at Goldman, recently raised his base-case forecast to 75,000 humanoid shipments in 2026, 890,000 in 2030, and 6.5 million in 2035, versus previous estimates of 51,000, 256,000, and 1.4 million, respectively.

"We are raising our humanoid robot market forecast. The global market is now projected to reach approximately 890,000 units by 2030 and 6.5 million units by 2035 (representing a $138 billion market opportunity)," Sheridan told clients in late August.

It's not just data centers that will drive memory demand. Physical AI could become the next major source of demand.

Tyler Durden Thu, 10/15/2026 - 14:35

Bitcoin Will Become "Less Volatile" And Larger Than Gold: 'The Bitcoin Standard' Author

Zero Hedge -

Bitcoin Will Become "Less Volatile" And Larger Than Gold: 'The Bitcoin Standard' Author

Authored by Zoltan Vardai via CoinTelegraph.com,

Saifedean Ammous, the author of the 2018 academic book "The Bitcoin Standard," said that Bitcoin already functions as a medium of exchange and that volatility's effect on that is likely to diminish.

Bitcoin (BTC) can serve as a medium of exchange as it becomes less volatile than gold while surpassing the market capitalization of the largest precious metal, wrote Ammous in a Tuesday X post.

"Holding Bitcoin is using Bitcoin as money, and its lack of widespread use as a method of payment is no evidence against its monetization unfolding," added Ammous.

The remarks come in response to a passage in Professor Lawrence H. White's book, "Better Money: Gold, Fiat, or Bitcoin?," which argued that Bitcoin's fixed supply makes it too volatile to serve as a medium of exchange.

"With no supply response to demand swings, BTC's price is too volatile for people who want a reliable medium of exchange," wrote White in a Monday X post, referencing chapter six of his book.

He added that the lack of supply response was the reason stablecoins have "eaten BTC's lunch transaction volume."

Other industry watchers have also predicted that Bitcoin would eventually surpass gold. In May 2025, Bitwise's head of European research, André Dragosch, told Cointelegraph that their in-house prediction forecasts a $1 million Bitcoin price by 2029, which would make Bitcoin match gold's market capitalization.

However, Bitcoin's current $1.6 trillion market capitalization would need to grow by at least 18-fold to surpass Gold's near $29 trillion market cap to become the leading global asset.

In April 2025, Blockstream CEO Adam Back predicted Bitcoin will start rivaling gold's use cases as a monetary hedge, due to global financial instability and rising fiat inflation.

Tyler Durden Thu, 10/15/2026 - 14:20

Think Rates Are Peaking? Consider Mortgage-Backed Securities

Zero Hedge -

Think Rates Are Peaking? Consider Mortgage-Backed Securities

Authored by Michael Lebowitz via RealInvestmentAdvice.com,

Think interest rates are peaking? If so, agency mortgage-backed securities (MBS) deserve a look. Think rates have further to climb? MBS may still earn a place in your fixed-income allocation, potentially offering more yield than Treasuries and essentially no credit risk.
Here is the twist. In 2022 and 2023, MBS investors learned a painful lesson. As rates surged, homeowners stopped refinancing, and MBS durations rose at the worst possible time. Today, that dynamic has largely run its course. With 30-year mortgage rates at 7.25% and nearly 80% of homeowners holding a rate below 6%, refinancing has all but stopped, leaving MBS durations little room to extend further. The feature that hurt MBS investors in 2022 and 2023 has little room for further harm.

MBS are a unique type of bond because mortgagees can prepay part or all of their mortgage at any time without penalty. Thus, MBS investors, who have essentially lent mortgagees money, are, inherently, short a prepayment option. The prepayment option accounts for much of the extra yield MBS offer over Treasuries, as well as their greater interest rate risk. But when the risks are limited, MBS holders are often in an advantageous position.

In this article, we weigh the pros and cons of MBS at current yields, explain what will drive future returns, and share how individual investors can gain exposure.

Setting The Stage

Mortgage rates and Treasury yields have moved sharply higher over the last six months. Per Freddie Mac, the average 30-year fixed mortgage rate was 7.28% as of October 1, the highest since November 2023, and up from 6.34% a year ago.
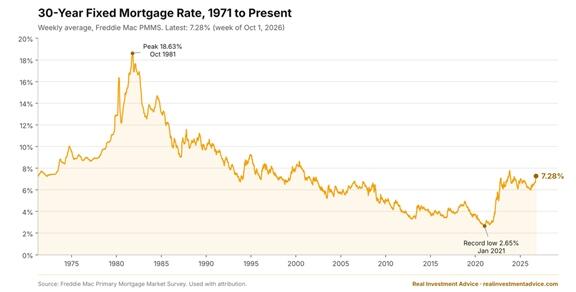
Source: Freddie Mac Primary Mortgage Market Survey, via Real Investment Advice

The graph above shows that virtually all mortgages originated from the early 2000s have a rate below the current rate. Accordingly, refinancing activity has dried up. To wit, the Mortgage Bankers Association (MBA) reported that its refinance index is over 50% below the same level a year ago. Per Joel Kan of the MBA:

Mortgage rates jumped to their highest level in almost three years, pushing borrowers to the sidelines.

The iShares MBS ETF (MBB), a reasonable proxy for the agency MBS index, holds securities with a weighted average coupon of 3.63%, roughly 3.50% below the current mortgage rate. With most mortgages at least 2% below current rates, very few homeowners have an economic reason to refinance.

In bond terminology, their prepayment option is worth little. To better understand why this matters for MBS investors, let's focus on MBS duration.

Understanding MBS Duration

Duration measures a bond's price sensitivity to changes in interest rates. A bond with a duration of seven years should lose about 7% of its value if yields rise by 1% and gain about 7% if yields fall by 1%. For Treasury, municipal, and corporate bonds, duration is fairly predictable because their interest and principal cash flows are fixed.

MBS investor cash flows depend on when and by how much homeowners pay down their mortgages, which depends largely on interest rates. Therefore, changes in interest rates have a much more profound impact on MBS durations than Treasury and corporate durations.

MBS investors track effective duration, a model-based duration estimate that accounts for how prepayments are expected to change as rates move.

  • When rates rise, refinancing slows, cash flows are pushed further into the future, and duration lengthens.
  • When rates fall, refinancing accelerates, principal comes back sooner, and duration shortens.

The graph below shows a hypothetical comparison of MBS and Treasury duration for a range of Treasury yield levels. Note how quickly MBS duration changes when rates are between 4% and 6%. At the same time, note the relatively flat, downward-sloping Treasury duration once rates are above 6%. The lower graph shows that refinancing activity is highly sensitive to rate changes when 10-year Treasury yields are in the 4% to 6% range.
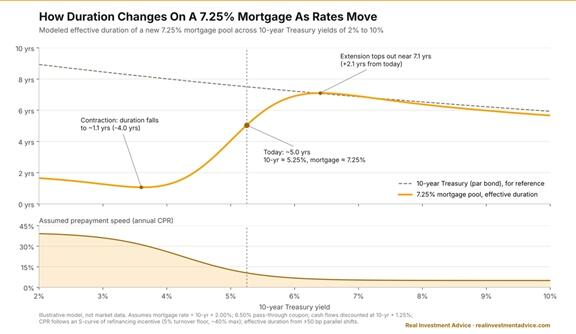
Source: Real Investment Advice (illustrative model, not market data)

Coping With Duration Shifts - Negative Convexity

The graph above shows that MBS rate exposure tends to shift in the wrong direction at the wrong time for investors. For instance:

  • Duration increases when yields rise, so price losses are greater than they would have been if duration had remained constant.
  • Duration declines when falling rates would otherwise produce larger price gains had duration remained constant.

Those negative consequences are called negative convexity.

This all means that the stated duration of an MBS or portfolio of MBS is a snapshot, not a constant. Investors should expect it to change as rates change and watch where current mortgage rates sit relative to the point at which homeowners can profitably refinance.

Extension Risk Is Largely Spent

Extension risk, or rising duration, has been harming MBS investors since rates started rising in late 2021. As rates rise, refinancing slows, the expected life of the mortgage pool lengthens, and duration increases precisely when investors least want more duration. MBS holders acutely felt the negative convexity in 2022 and 2023.

Today, despite the recent rate increase, much of that extension has already occurred. When a mortgage pool is deeply out of the money, or not economically refinanceable, as many are today, prepayments are driven almost entirely by factors unrelated to interest rates such as:

  • Home sales.
  • Scheduled amortization of principal.
  • Defaults, which, for agency MBS, return principal at par.
  • Cash-out refinancing, which is limited at current rates.

These and other sources of principal repayment create a floor under prepayment speeds.

Today, prepayments can't slow much more; thus, further rate increases would not extend duration much. Put differently, MBS investors buying today are taking on duration that is relatively capped on the upside. Accordingly, the risk/reward for MBS looks more balanced than it did a few years ago.

The Con: The Double Whammy If Rates Fall

The flip side of limited duration extension risk is the MBS problem when rates decline. If mortgage rates fall meaningfully, higher-coupon pools face two penalties at once:

  • Principal earning higher rates returned through prepayments must be reinvested at lower rates.
  • Duration shortens. As refinancing accelerates, the expected life of the MBS declines, capping price appreciation relative to a comparable Treasury.

This is the cost of the prepayment option MBS investors essentially sold to homeowners. The extra yield they earn over Treasuries is the premium they are paid for bearing it.

The Silver Lining To The Double Whammy

Within the double whammy, i.e., negative convexity, lies a potential reward in today's market. If mortgage rates fall by almost 2.5% to 5%, over two-thirds of mortgages, as we share below, have no financial incentive to refinance.
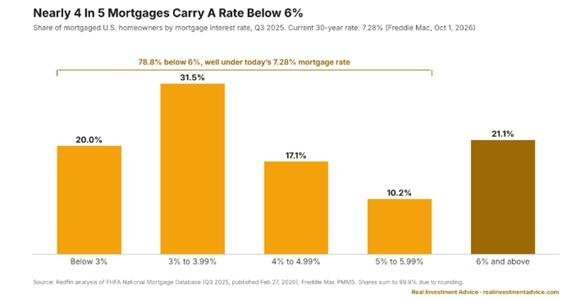
Source: Redfin analysis of FHFA National Mortgage Database (Q3 2025); Freddie Mac PMMS, via Real Investment Advice

For most of the MBS market, falling rates in the recent environment are a good thing:

  • Because refinancing will be slow to kick in, duration declines should be minimal; investors can capture a large amount of the price benefit of lower yields.
  • Faster prepayments become a gain. Lower rates tend to boost home sales, and every sale pays off a loan at par. For MBS trading below par, each dollar returned early is profit pulled forward.

Bear in mind it's not just the low number of high-rate loans that will likely limit prepays when rates fall. Refinancing takes months for borrowers to notice lower rates, shop lenders, and close loans. Furthermore, given the lack of recent refinancing and home sale activity, lender capacity could become a bottleneck if applications surge.

Also, many borrowers never refinance. Some lack the credit score or home equity to qualify, some have balances too small to justify closing costs, and others simply do not act. As a result, investors continue to collect above-market coupons on the loans that remain.

Falling rates can be very beneficial to MBS holders given today's backdrop.

How To Invest In MBS

For institutional investors, the agency MBS market is one of the deepest and most liquid fixed income markets in the world. Owning individual MBS is ideal in theory. It allows investors to choose the coupon, vintage, and prepayment characteristics that best fit their views. However, in practice, it is challenging and impractical for smaller investors for the following reasons:

  • Pools factor down. Every month, a portion of principal is returned. A $100,000 position may be $60,000 within a few years, and small, "odd-lot" positions trade at meaningful discounts to larger pools.
  • Monthly principal must be reinvested. Small, irregular cash flows are difficult to put back to work efficiently.
  • Prepayment analysis requires data and models most individual investors do not have.
  • Dealer access and pricing transparency for small trades are limited.

For these reasons, an ETF or mutual fund may be a more practical option for smaller investors. Funds handle reinvestment, maintain diversification across coupons and vintages, and benefit from professional management, institutional models, and lower trading costs.

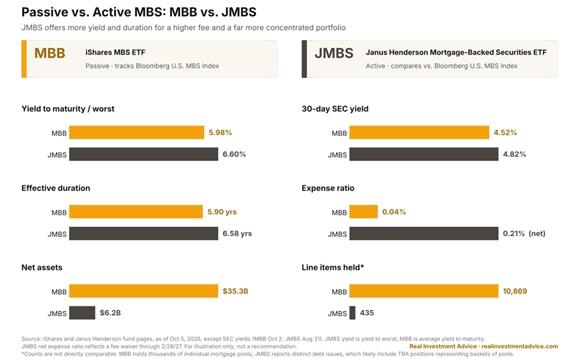
Passive ETFs such as MBB offer broad index exposure at low cost; its expense ratio is 0.04%. Actively managed MBS funds, such as JMBS, can shift their holdings toward coupons and specified pools that managers believe offer better convexity profiles, albeit at higher fees.

Investors should review a fund's coupon distribution, effective duration, and use of leverage or derivatives. Two funds with similar durations can behave differently.

The graphic below compares the most popular passive MBS ETF, MBB, to the largest active ETF, JMBS.
Source: iShares, Janus Henderson fund pages (as of Oct 5, 2026), via Real Investment Advice

Summary- Investment Thesis

A bullish thesis rests on two key points. First, interest rates stabilize and start to fall.

Second, even if rates rise, the duration shift is largely capped, as the graph below shows. Accordingly, assuming MBS-to-Treasury spreads do not change, the price change between an MBS and a similar-maturity Treasury will not be that indifferent.

Three years ago, extension risk was the reason to avoid MBS. Today, it is one reason to own them. With most mortgages far below market rates, MBS duration has little room left to extend or refinance. Investors are left with an asset class that offers high yields, minimal credit risk, and stable duration.

Tyler Durden Thu, 10/15/2026 - 13:50

Lisa Cook's Attorney Challenges Fairness Of White House Probe

Zero Hedge -

Lisa Cook's Attorney Challenges Fairness Of White House Probe

Authored by Matthew Vadum via The Epoch Times,

Federal Reserve board member Lisa Cook's attorney called into question the fairness and objectivity of a White House probe after President Donald Trump announced a new committee to investigate whether Cook made false statements.

In an Oct. 13 letter to White House counsel William Scharf obtained by The Epoch Times, lawyer Abbe Lowell wrote that one proposed member of the committee that will review the allegations against Cook, White House economic policy adviser Kevin Hassett, had previously pressed Cook to go on leave from her office and said Trump had "cause" to fire her.

A year ago, Hassett said Cook's refusal to step aside was "a partisan stance contrary to the independence of the Fed." Lowell said this comment suggests that he has prejudged the case.

The White House has proposed a Nov. 5 in-person hearing with Cook.

"A hearing with demonstrably biased members, unspecified additional allegations, and an unclear schedule for the disclosure of any additional evidence - with no explanation for why it was not previously produced - is not a process that respects the appearance or history of independence" of the Fed, Lowell wrote.

These are some of the issues that would have to be addressed before a hearing could take place, he said.

The Oct. 13 letter from Lowell comes days after Trump unveiled the new committee to investigate whether Cook made false statements.

The committee will probe allegations that Cook provided false information in connection with at least one mortgage instrument, Trump said in a presidential memorandum establishing the panel.

Trump later told reporters he would fire Cook if the committee were to recommend it. Cook's attorneys have said a fair hearing would demonstrate that the president has no legal basis for firing her.

Lowell said Cook will not be able to appear at the November hearing because she will be in Europe attending financial and monetary policy meetings. The earliest she is available is after the Fed's policy meeting set for Dec. 8 and Dec. 9, he said.

On June 29, the Supreme Court blocked the firing, rejecting Trump's arguments that he could avoid judicial review. The 5-4 decision said Cook was "entitled to notice and some opportunity to respond before her termination."

The ruling outlined a path for possibly removing Cook if she were given a chance to review the evidence and afforded an opportunity to refute it, which appears to be the path the White House is pursuing.

Trump said he followed the provisions of the Federal Reserve Act, which he said permits presidents to remove board members "for cause."

White House spokesperson Matthew Middleton defended the process, saying the Constitution requires the president to ensure that laws are followed and that the conduct of Fed governors "is above reproach."

"The President is going beyond what the Supreme Court required by offering Lisa Cook an in-person hearing that will be conducted in a fair and open process," he told The Epoch Times.

A White House official said the committee will consist of a senior economist and expert on the Federal Reserve, an employment law expert, and an expert in government ethics. Cook's hearing will be on the record, and she will be allowed to be represented by an attorney. She will be given the evidence in advance and will have an opportunity to present her own written evidence, as well as written witness statements, the official said.

President Joe Biden appointed Cook as one of the Federal Reserve's board members in 2022 and reappointed her in 2023. Both times, Cook was confirmed by the U.S. Senate.

Zachary Stieber and Sam Dorman contributed to this report.

Tyler Durden Thu, 10/15/2026 - 12:20

Currie Slams 'Vibe' Oil Contracts As Trump Admin Halts SPR Drains, IEA Urges Massive Reserve Release

Zero Hedge -

Currie Slams 'Vibe' Oil Contracts As Trump Admin Halts SPR Drains, IEA Urges Massive Reserve Release

Oil prices are extending gains again this morning as traders weigh a weaker global demand outlook and signs of recovering Middle East crude supplies against persistent shipping risks around the Strait of Hormuz and escalating/spreading violence between the Houthis and Saudis.

An overnight lull in prices (set with hopes for more reserve releases) was upset as Iran showed more clips of tankers/container ships under attack.

The International Energy Agency said Wednesday that Gulf crude shipments rose by 4.4 million barrels a day to 13.9 million barrels a day in September, reaching more than 75% of prewar levels. Global oil supply increased by 2.5 million barrels a day to 102.3 million barrels a day, driven by Gulf producers.

However, the recovery remains vulnerable to renewed attacks on energy infrastructure and shipping, the agency said.

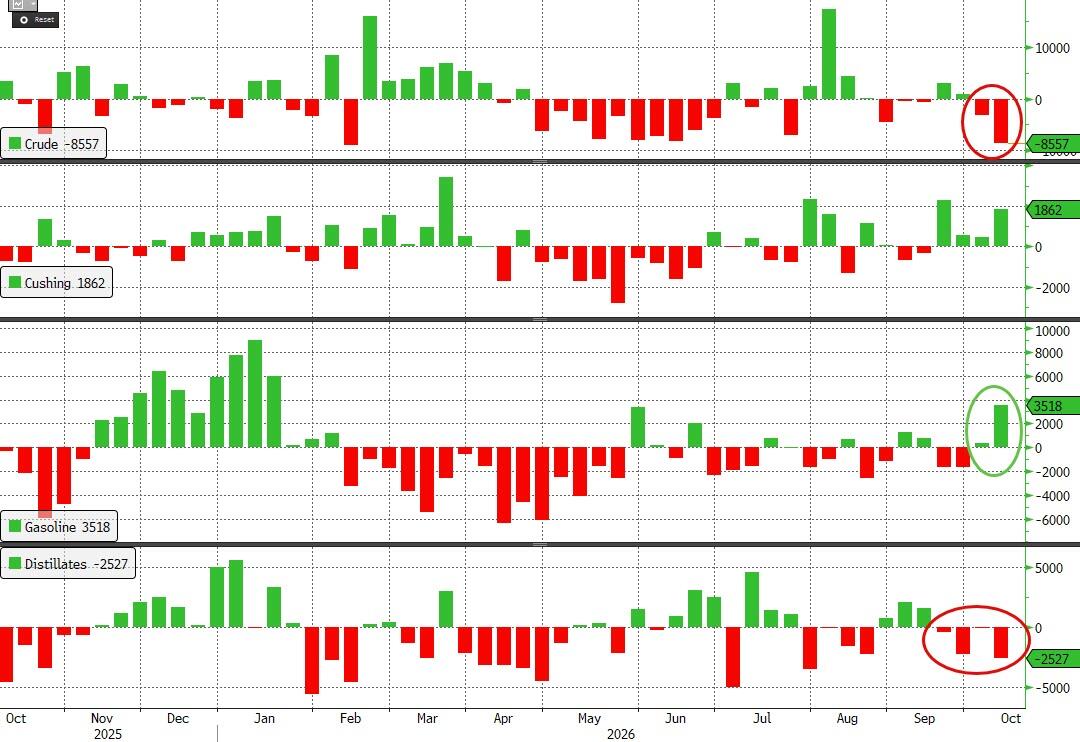
Given the massive crude draw reported by API (likely impacted by shut-ins from the first Atlantic hurricane of the year in the US Gulf), all eyes are on the (Columbus Day-delayed) official data...

API

  • Crude -11.1mm

  • Cushing +1.8mm

  • Gasoline +1.1mm

  • Distillates -1.5mm

DOE

  • Crude -8.56mm

  • Cushing +1.86mm

  • Gasoline +3.52mm

  • Distillates -2.52mm

HUGE CAVEAT - the shut-ins in the Gulf make this very noisy: Confirming API's reporting, the official data showed a large crude draw last week (and another sizable draw in distillates inventories) while stocks at Cushing and overall Gasoline inventories saw builds...

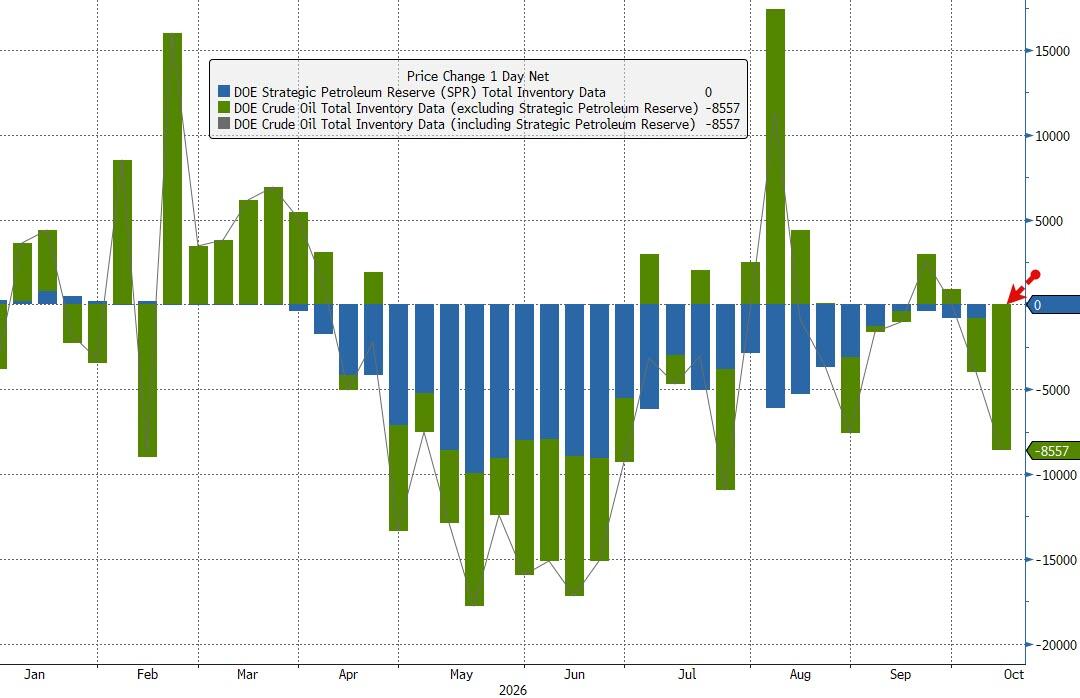
For the first time since the Iran war began, the Trump admin did not drain any reserves from the SPR...

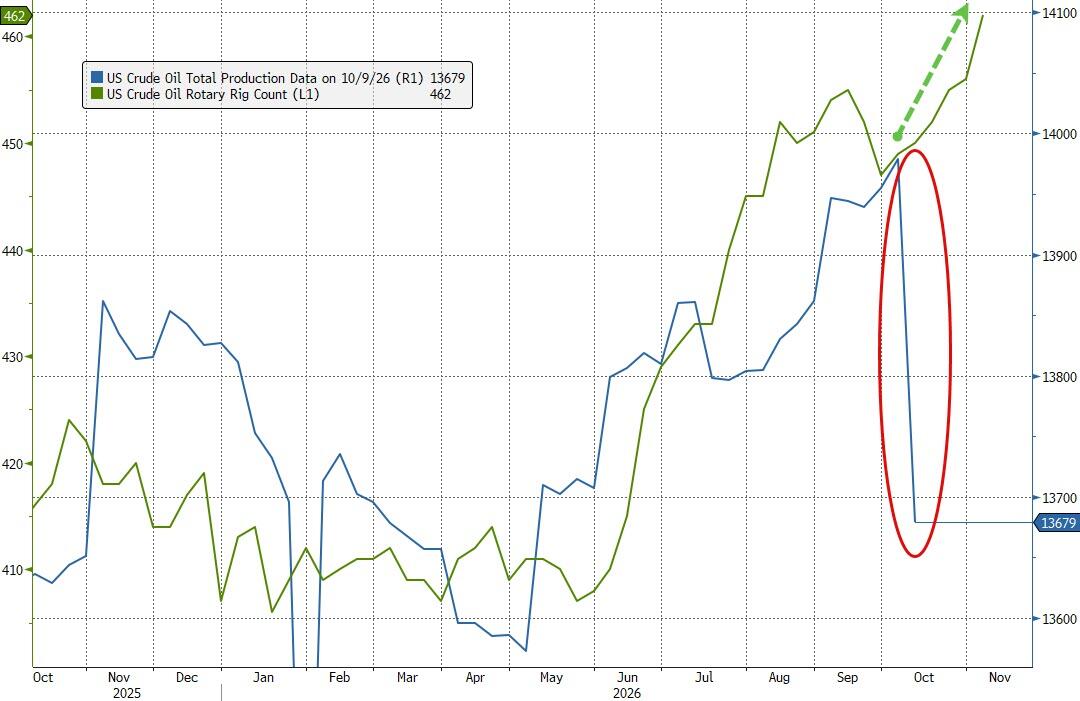
US Crude Production tumbled last week (shut-ins in the Gulf, so not comparable)...

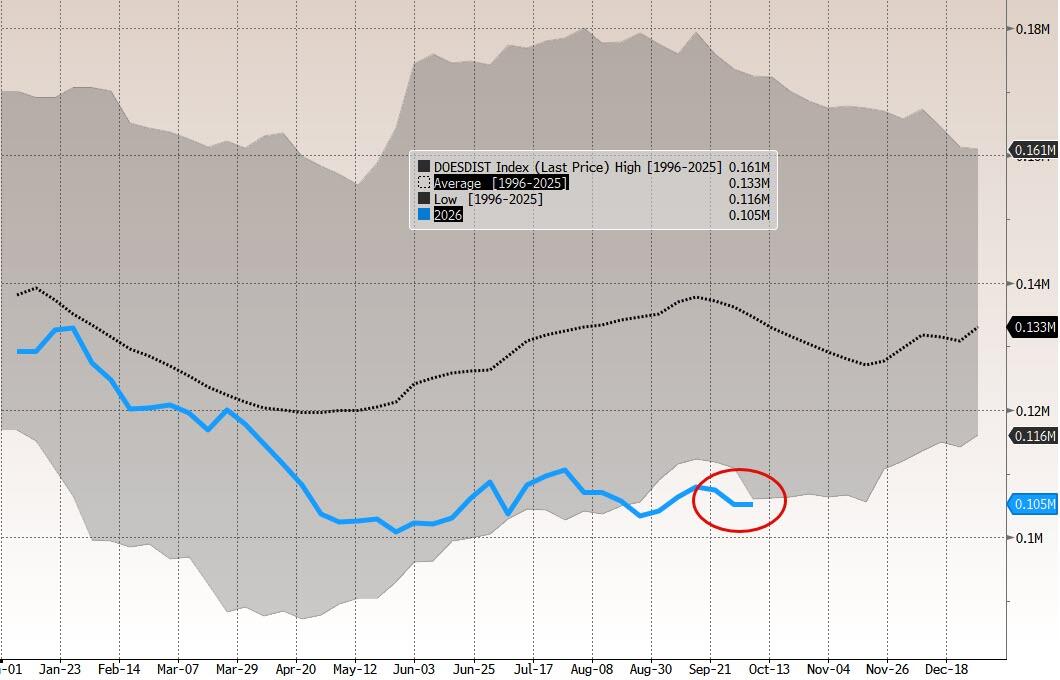
Total US Diesel stocks remain at seasonal record lows...

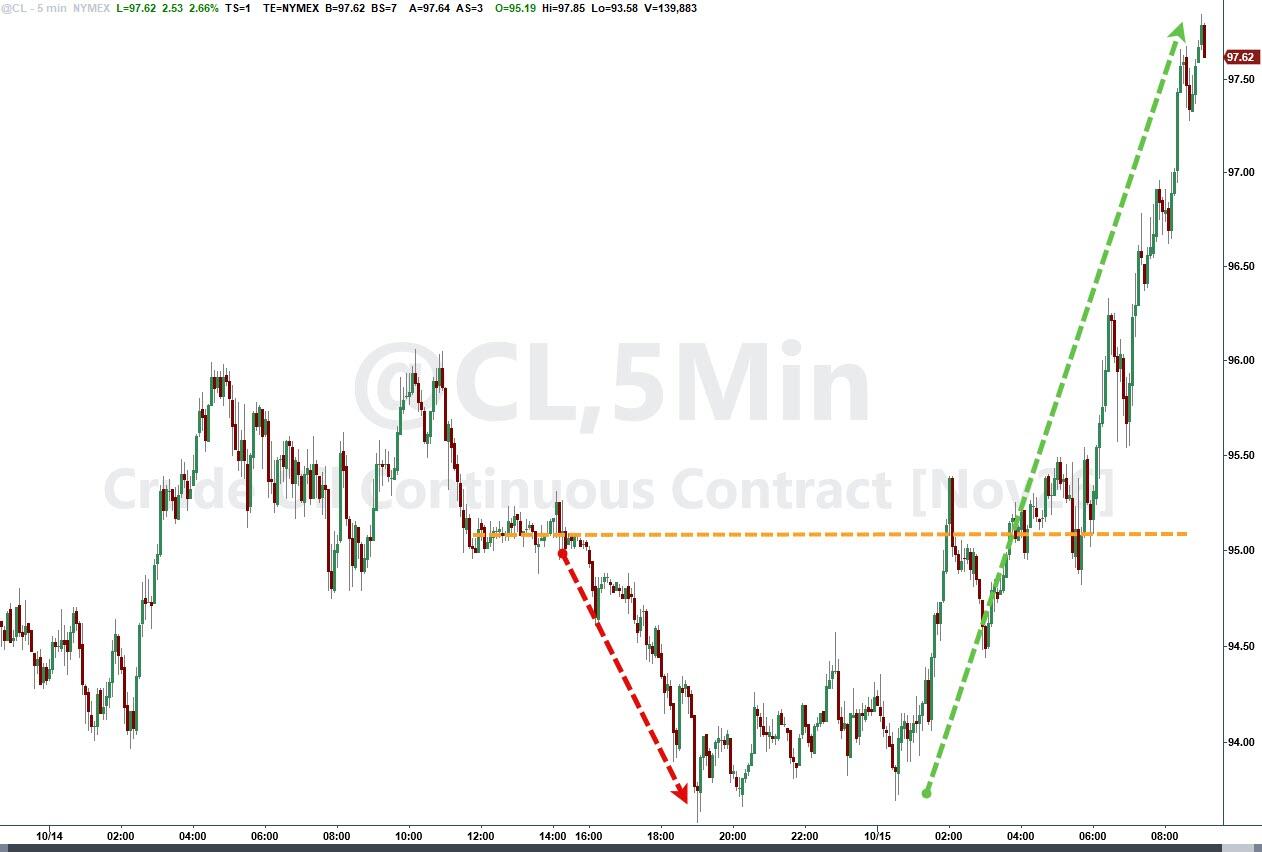
WTI has surged up to $97.50

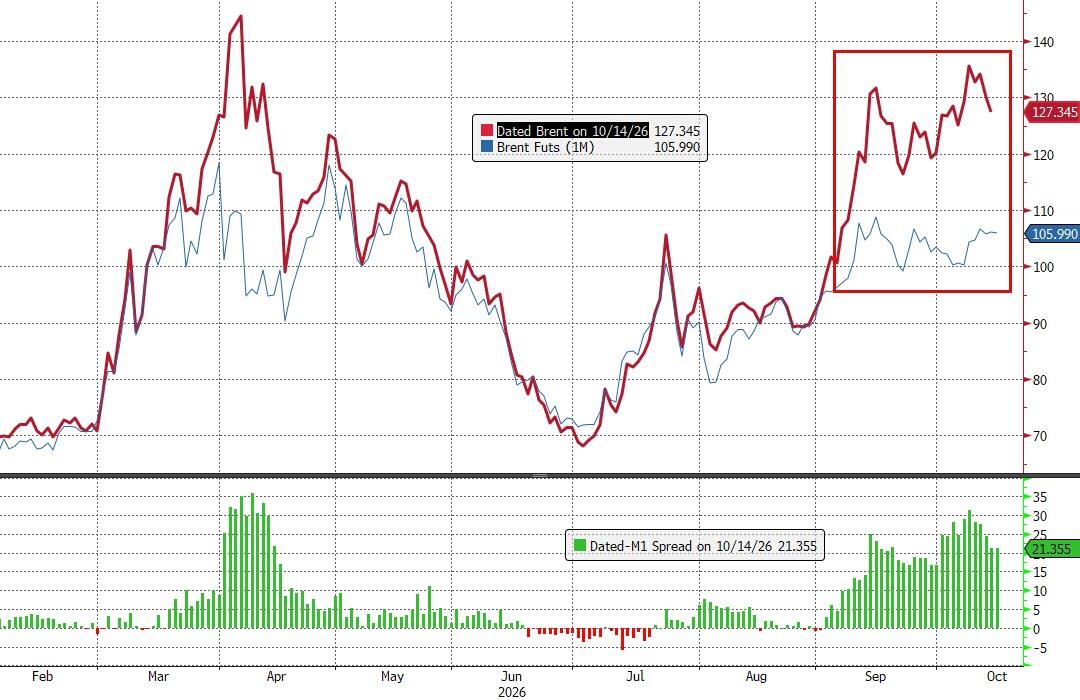
However, watching futures is misleading as Wall Street veteran Jeff Currie exclaimed this morning that the world’s most important oil benchmark has become little more than a “vibe contract", blunting its usefulness as a tool to manage price volatility.

Brent’s disconnect from physical markets is creating “unpriceable risk,” deterring hedgers from using the contract to protect themselves, Currie said.

“Everything associated with energy is going up but Brent,” Currie said Thursday in an interview on Bloomberg Television.

“It is not connected to the real world anymore.”

A hit to Brent’s integrity undermines the market’s ability to anticipate supply shocks with “profound consequences for the market and the rest of the world,” Currie said.

The disconnect between paper and physical markets has frustrated traders since the Middle East conflict began, when crude struggled to top $100 despite historic supply shortages. In contrast, Dated Brent, the most important physical oil benchmark, has surged to near $130 a barrel. That dissonance has contributed to traders fleeing the market, with Brent open interest earlier this month hitting its lowest since March 2025 even as oil dominates headlines.

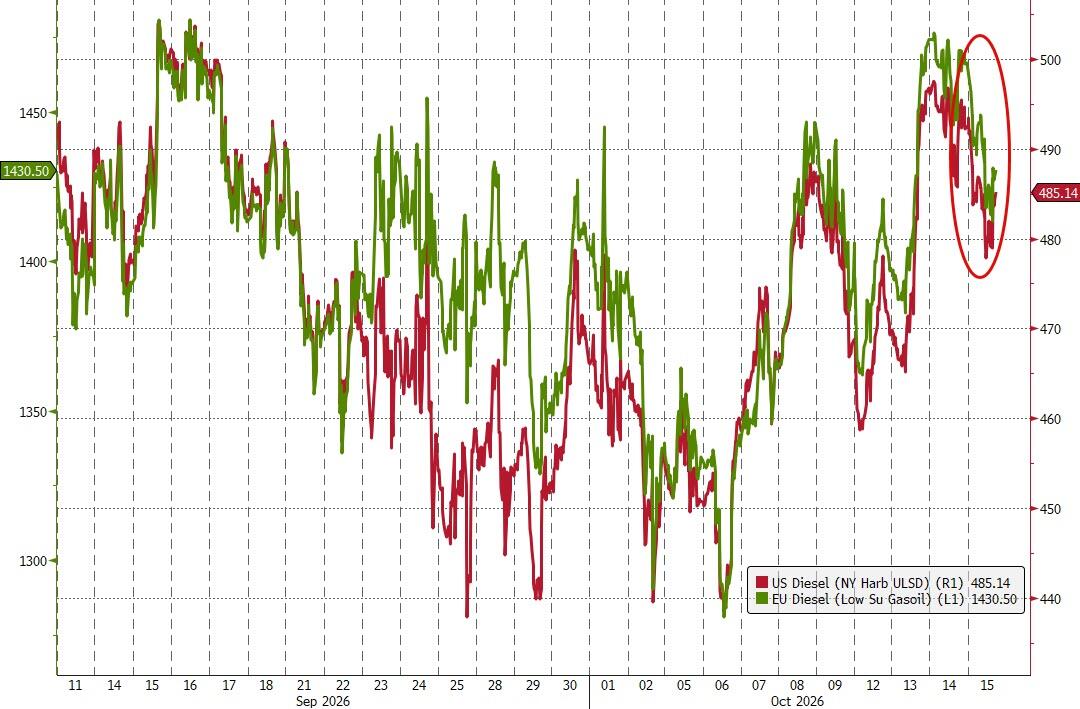
Diesel prices are lower this morning...

Finally, Bloomberg reports that US officials attending an International Energy Agency meeting in Paris earlier today informally lobbied allies to commit an additional 100 million barrels from emergency oil inventories to supply global markets. 

"While US officials attending an IEA gathering in Paris on Thursday have yet to table a proposal about what should be done, they have been informally lobbying for an extra commitment of at least 100 million barrels, the people said, asking not to be identified because the matter is not public." (BBG)

The report says US officials believe IEA members have not released enough oil from the coordinated 400 million-barrel oil and fuel release announced in March to cushion the impact of the Gulf conflict.

The Group of Seven nations agreed earlier this month to release up to 100 million barrels after President Trump threatened Europeans with a halt to exports of diesel and other petroleum products.

Today's request follows Trump's deal with Moscow to supply US and global markets with thousands of tons of diesel fuel.

On top of this, a defiant President Volodymyr Zelenskyy told the Financial Times earlier today that his armed forces will attack Russian refineries once again. This comes after the Trump administration requested that Ukraine stop hitting Russian refineries, as those attacks have been one of the drivers of the global refining crisis.

Last month, IEA head Fatih Birol said about one-third of the 400 million-barrel release announced in March had been delivered to global markets. Meanwhile, US SPR inventories have fallen to levels not seen since the early 1980s.

The Trump administration's scramble comes as midterm elections are just three weeks away. The latest credit and debit card data from Bank of America show that US consumers are spending more on fuel at the pump, crowding out other purchases and weighing on consumer sentiment.

Tyler Durden Thu, 10/15/2026 - 12:10

After Jensen Saves The World, Nasdaq Breaks

Zero Hedge -

After Jensen Saves The World, Nasdaq Breaks

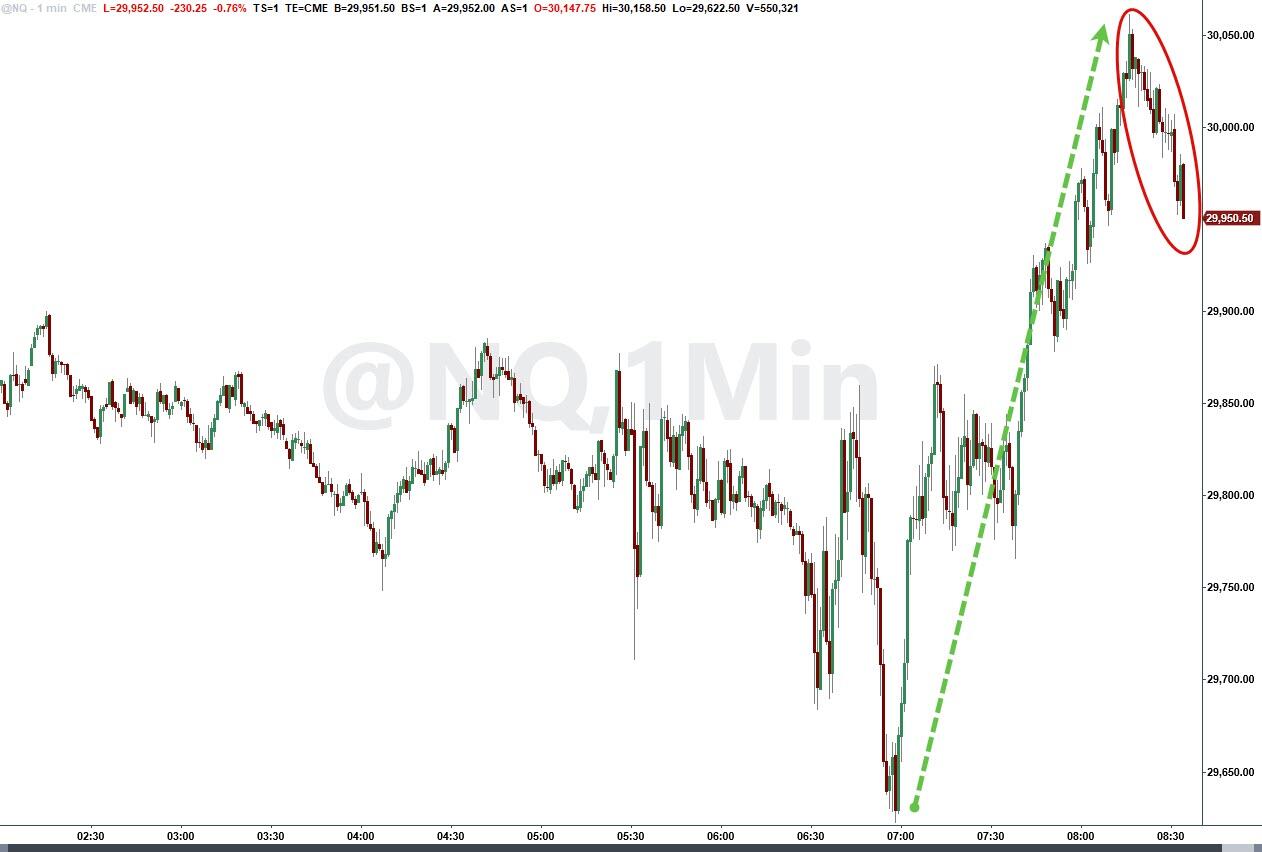
Nasdaq has been soaring higher for the last hours following supportive statements from Nvidia CEO Jensen Huang:

  • HUANG: "COREWEAVE'S STRENGTH IS IMPROVING EVERY DAY"

  • HUANG: COREWEAVE'S COST OF CAPITAL IS "ACTUALLY DECREASING"

  • HUANG SAYS NVIDIA DOESN'T NEED TO BACKSTOP COREWEAVE

As a reminder, Nvidia helped rescue CoreWeave's downsized IPO and holds a ~$2 billion stake.

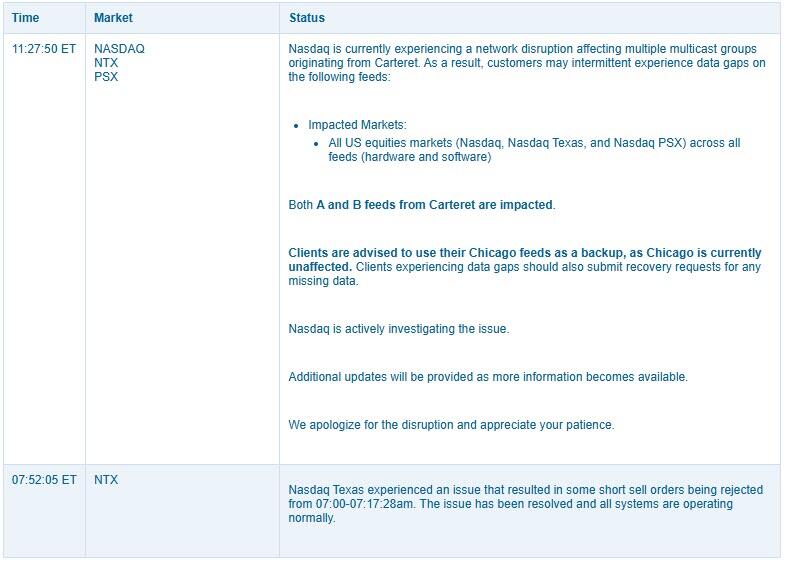
Then around 1115ET, Nasdaq broke...

Nasdaq is experiencing a network disruption affecting multiple multicast groups originating from Carteret, according to a market system status message.

Nasdaq warned that customers may experience intermittent data gaps on all US equities markets (Nasdaq, Nasdaq Texas, and Nasdaq PSX) across all feeds (hardware and software)

And the market rolled over...

...maybe Nasdaq should have used a CoreWeave data-center?

Tyler Durden Thu, 10/15/2026 - 11:57

Trump Admin Floats Unfreezing Russian Assets In Big Move To Restart Talks

Zero Hedge -

Trump Admin Floats Unfreezing Russian Assets In Big Move To Restart Talks

President Trump appears to be busy rolling back years of entrenched Ukraine policy. Starting last week he announced the controversial diesel deal with Putin, and this week Ukraine's Zelensky is complaining that intelligence-sharing has been throttled, and possibly even cut off.

The possibility or even likelihood of this heading to another TACO moment aside, what's next? New reporting in the Financial Times gives an idea. The United States has floated a proposal that European countries unfreeze some of Russia's sovereign assets and deposit them in an entity controlled by Washington.

via Associated Press

The FT report cites four people familiar with the matter, who describe that the idea was formally presented by envoys Steve Witkoff and Jared Kushner during a meeting of Western allies and Ukraine in Miami on Oct.10.

"The US suggested several possible methods for unfreezing the assets, including for them to be moved into a new special-purpose financial vehicle overseen by Washington," the sources said.

This US plan would be enacted in the hope of opening up momentum toward a comprehensive Ukraine peace plan. Moscow has of late rejected any 'temporary' proposal, including a 60-day pause in fighting recently offered by Zelensky. It wants a lasting political settlement and not a mere 'pause' along the front lines.

At the Miami meeting were NATO representatives, as well as officials from the US, France, Germany, and the EU.

"Many ideas have been floated as to how Moscow's frozen assets could be used after the war, the US official added," the FT says.

European officials are said to have balked at any initiative to let go of Russian assets. "They were told that this was just simply not going to happen," one source said. For example, Germany has voiced its clear position:

"Those are assets that are frozen ​in Europe and they should remain frozen in Europe. ​This is our business and we are deciding over ⁠it," Merz said in Brussels ahead of an EU ​summit.

At least €260 billion in sovereign assets belonging to Russia's central bank were frozen in 2022 as a result of Russia's full-scale invasion of Ukraine in February of that year. Most of this is held at the Belgian securities depository Euroclear. The vast majority, or over €210 billion of the sum, is held in the EU.

The last couple years of war has seen the EU work out a scheme wherein payments are made to Ukraine utilizing interest gained from Russa's funds.

Washington's sudden willingness to ease off the pressure on Moscow has interesting implications regarding the Iran war...

European Commission President Ursula von der Leyen said that Moscow "must pay for the destruction it has caused. And we are using the proceeds from the immobilized Russian assets to make sure it does."

"We are making a further [$1.62] billion of them available to Ukraine. This will support Ukraine's continued resistance against Russia's illegal war," she had announced in August.

Tyler Durden Thu, 10/15/2026 - 09:40

Suspected ISIS Bomber Lived In UK Taxpayer Hotel After Small Boat Arrival

Zero Hedge -

Suspected ISIS Bomber Lived In UK Taxpayer Hotel After Small Boat Arrival

Authored by Steve Watson via Modernity.news,

Reports have emerged of a suspected ISIS operative and alleged rapist being housed in a taxpayer-funded hotel following his illegal arrival in the UK.

"Britain is getting the dregs," GB News presenter Patrick Christys urged, reacting to the case of an Iraqi man who crossed the Channel, gave a false name, and lived undetected for weeks before German authorities tipped off the UK National Crime Agency.

Layth Ibrahim Mohammed, 39, is accused of links to Islamic State in Iraq during the 2010s, including making booby-trapped bombs and teaching the children of ISIS fighters at a school run by the group.

He arrived by small boat from France in August 2025, claimed asylum, and was placed in a Home Office hotel in Oldham, Greater Manchester. NCA officers arrested him there in October 2025, but only after Germany flagged his background.

He is now fighting extradition to face terrorism-related charges and an allegation of raping a German woman. The allegations have not been established in court.

His lawyer, Joanna Curtis, told a Westminster hearing that extradition would be inhumane because "he has significant mental health issues, including severe anxiety, as well as depression." She linked the trauma to a bomb attack in Iraq that killed his son and even laughably cited symptoms of "pins and needles."

This is not an isolated failure. Earlier this year, another ISIS-linked man reached Britain the same way after social media reassured him the UK takes everyone.

Mohammed Yaseen, previously convicted in Germany for ISIS membership, attended beheadings and floggings in Iraq, then crossed after watching TikTok videos claiming Britain "accepts everyone and respects human rights."

He gave false details, was processed, and only later identified by biometrics. Prosecutors described him as high risk.

The pattern is clear: people with documented extremist histories clear the Channel, destroy or withhold documents, and enter the asylum system before any meaningful check occurs.

The scale makes individual cases inevitable. Small-boat arrivals since Labour took office have already surpassed the strength of the British Army.

More than 83,000 crossed between July 2024 and September 2026, exceeding the Army's roughly 83,000 regulars and outnumbering the Navy and RAF combined.

Total arrivals since 2018 top 200,000. The vast majority are military-aged men. Shadow Home Secretary Chris Philp called it "completely bonkers," noting Labour had "let an entire army-sized population cross the Channel illegally."

Reform leader Nigel Farage has repeatedly warned the crossings represent a national security emergency.

At this week's Prime Minister's Questions he pressed Andy Burnham directly: "Every week there are young, unidentified males from Iran coming into this country, some of whom pose a genuine security threat to our nation. Is it not time the Government recognises that what is going on in the English Channel is a national security emergency?"

Burnham replied that crossings were "coming down" and removals were up, while acknowledging more needed to be done. Farage has described the situation as an "out-of-control disaster."

The numbers are not sustainable on any measure. Settlement grants alone have reached one every minute.

Home Office data show 140,000 grants of settlement or citizenship in a single three-month period. Asylum system costs hit £4.3 billion in one year. Fewer than 5 percent of Channel arrivals since 2018 have been removed.

Foreign nationals are disproportionately represented in certain offence categories, including sexual offences. The system continues to grant status and benefits while the backlog of appeals grows.

Much of this rests on claims that officials themselves describe as fraudulent. A Home Office caseworker with years of experience processing thousands of applications stated that "at best 1 per cent of asylum seekers are genuine."

Identical "package claims," recycled stories, and fabricated evidence are routine. Networks coach applicants for thousands of pounds. Staff are instructed to treat claimants as "customers." Modern slavery claims are nearly impossible to disprove and routinely succeed.

The result is a system that rewards illegal entry while genuine refugees and British citizens compete for housing, healthcare, and public resources.

Local authorities have responded to public concern by locking down entire towns rather than stopping the boats. In Gosport, police used multiple public-order powers to restrict residents, ban face coverings, and disperse gatherings so that hundreds of unvetted men arriving on mega-dinghies could be moved in luxury coaches.

Anti-migrant protesters faced arrests; an activist who slashed a dinghy was remanded in custody for months. The contrast with the rapid bail of terrorism suspects elsewhere is stark. Residents are treated as the problem while arrivals with unknown backgrounds are protected and housed.

These cases - ISIS suspects in hotels, arrivals outnumbering the Army, a system insiders call a scam, and towns placed under lockdown to facilitate landings - are not separate scandals. They are the predictable outcome of a policy that prioritises processing over screening, accommodation over removal, and international obligations over the security of the existing population.

Farage has called for the Royal Navy in the Channel and a pause on asylum claims. Successive governments have preferred payments to France and further hotel contracts.

The result is visible on the Kent coast, in Oldham hotels, and in the courtrooms where extradition is contested on mental-health grounds after the individual has already lived at public expense.

Britain cannot indefinitely absorb unvetted military-aged men, some with documented terror links, while maintaining public safety, housing stock, and basic services.

British society rests on a basic social contract: the state collects taxes and enforces laws in return for protecting the people who already live here. That bargain is rapidly fraying in real time.

The patience that has sustained decades of mass illegal entry is not unlimited. Once enough people conclude the state will not prioritise their safety, their housing, or their taxes, the remaining consent that keeps the system functioning quickly erodes. That is the edge the current policy has reached.

Tyler Durden Thu, 10/15/2026 - 09:25

Pages